
Kiwibank mortgage rates NZ: how to read them and get a better deal
Kiwibank mortgage rates are the advertised home loan rates Kiwibank sets for each fixed term and its floating loans. The advertised rate is a starting point. What you actually pay depends on your deposit, your income and whether Kiwibank or another lender is competing for your loan. An adviser can often get a sharper rate […]
Westpac mortgage rates NZ: how to read them and get a better deal
Westpac mortgage rates are the advertised home loan rates Westpac sets for each fixed term and its floating loans. The advertised rate is a starting point. What you actually pay depends on your deposit, your income and whether Westpac or another lender is competing for your loan. An adviser can often get a sharper rate […]
ASB mortgage rates NZ: how to read them and get a better deal
ASB mortgage rates are the advertised home loan rates ASB sets for each fixed term and its floating loans. The advertised rate is a starting point. What you actually pay depends on your deposit, your income and whether ASB or another lender is competing for your loan. An adviser can often get a sharper rate […]
BNZ mortgage rates NZ: how to read them and get a better deal
BNZ mortgage rates are the advertised home loan rates BNZ sets for each fixed term and its floating loans. The advertised rate is a starting point. What you actually pay depends on your deposit, your income and whether BNZ or another lender is competing for your loan. An adviser can often get a sharper rate […]
ANZ mortgage rates NZ: how to read them and get a better deal
ANZ mortgage rates are the advertised home loan rates ANZ sets for each fixed term and its floating loans. The advertised rate is a starting point. What you actually pay depends on your deposit, your income and whether ANZ or another lender is competing for your loan. An adviser can often get a sharper rate […]
NZ interest rate predictions: what the banks expect for 2026–2028
The RBNZ OCR track and each major NZ bank’s view, and what it means for choosing a fixed term now.
Refixing before the 28 October OCR? How I’d think about it
The OCR is 2.75% after two hikes and the next decision is 28 October. When to refix your mortgage, how to pick a 1, 2 or 3 year term, and why you should ask about cashback.
Mortgage break fees in NZ: how banks work them out, and why many are small right now
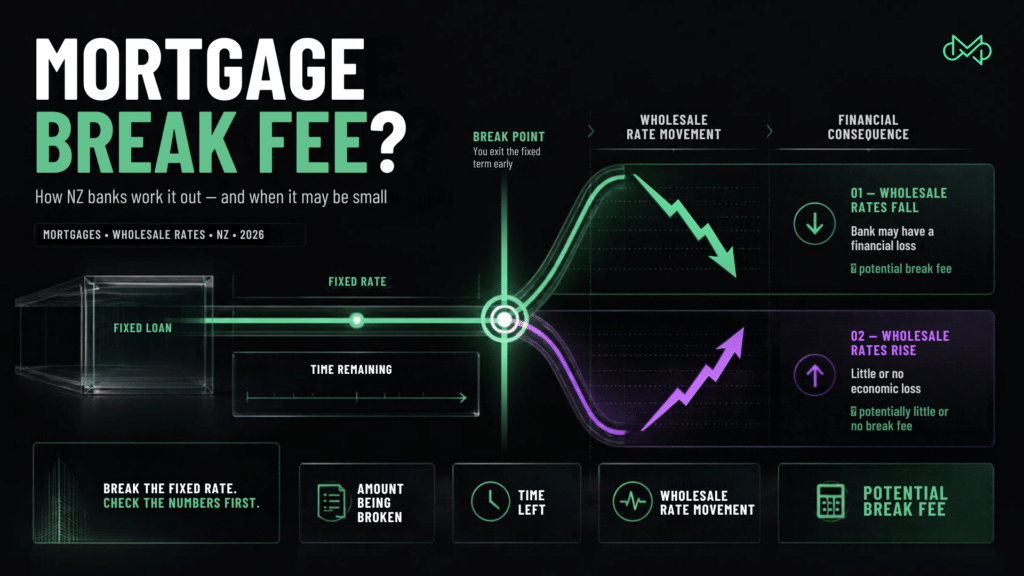
A break fee is the bank’s lost interest, not a penalty. How NZ banks calculate it, why many break fees are small while wholesale rates are rising, and how to tell whether breaking to refinance saves you money.
Comparing home loan rates in NZ: why the lowest rate isn’t always the cheapest loan
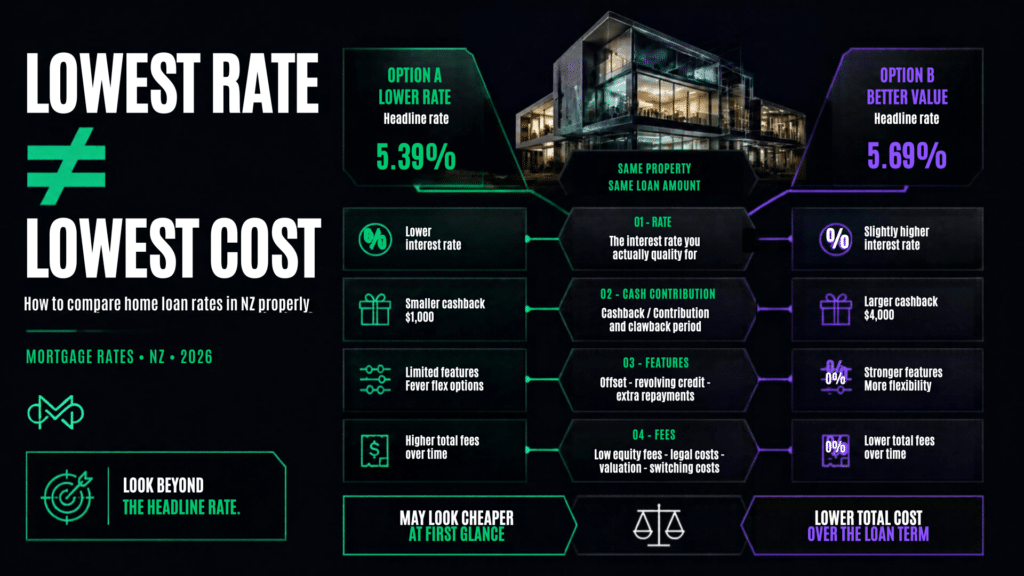
The lowest advertised rate is a starting point, not an answer. How to compare home loan rates in NZ once equity, cash contributions, clawbacks and loan features are counted.
Fixed or floating? How to choose when your mortgage rate comes off in NZ
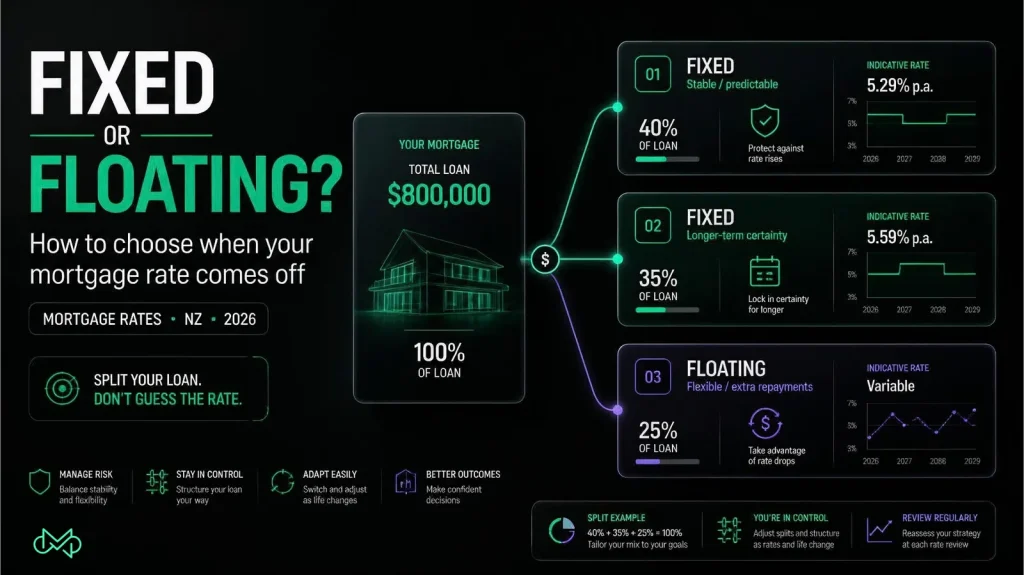
Your fixed rate is ending and the OCR has gone up twice since July. How to choose between fixed and floating, which term to pick, and why splitting the loan usually beats trying to call the market.
OCR announcement dates NZ for 2026 and 2027, and what each decision means for your mortgage
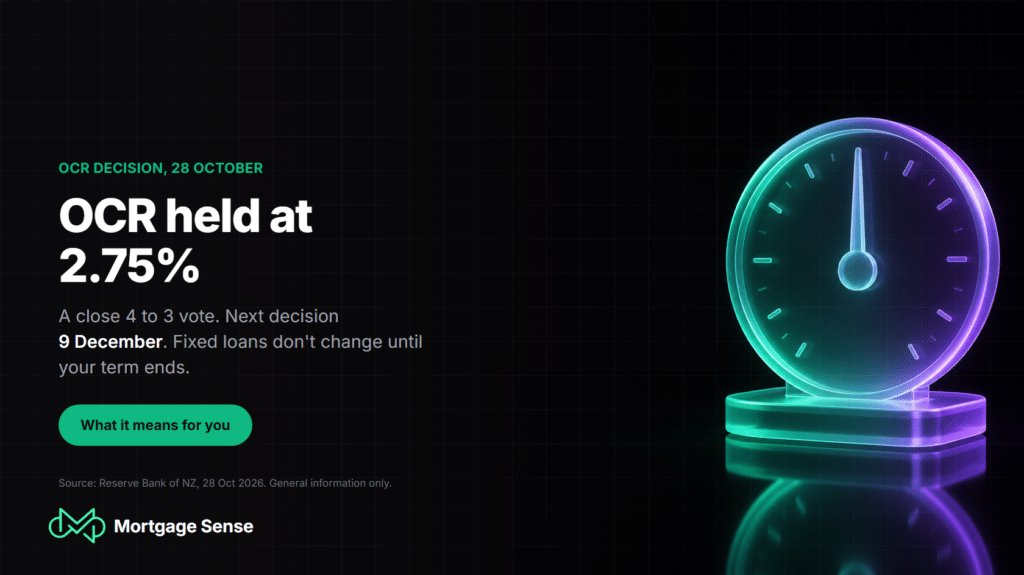
The next OCR announcement dates in New Zealand, where the official cash rate sits now, and what an OCR change actually does to floating and fixed mortgage rates.
Is Now the Right Time to Buy Property in NZ? What 2026 Might Mean for Home Buyers
There’s been a lot of quiet discussion lately about where NZ interest rates and the New Zealand property market may be heading in 2026. While nothing is certain, many people are starting to wonder whether the current conditions might be offering a window of opportunity one that may not look the same a few months […]