-
The Kāinga Ora Maintenance Clause (for First Home Loans)
If you intend to buy your first home using the Kāinga Ora low deposit First Home Loan scheme then you need to be aware of the eligibility and the maintenance clause that they have – Kāinga Ora require that any maintenance on the property cost less than $10,000 to repair and you need to both…
-
Due diligence clause NZ: what it covers and how it fits with finance
What a due diligence clause covers when you buy a house in NZ, how long it should be, how it fits with your finance condition, and what happens if you pull out.
-
Kāinga Ora First Home Loan: who qualifies and how it works
Who qualifies for the Kāinga Ora First Home Loan, the income caps, the 1.2% premium, whether there’s a house price cap, and how to apply through a participating lender.
-
OCR announcement dates NZ and what the OCR means for your mortgage
The next OCR announcement dates in New Zealand, where the official cash rate sits now, and what an OCR change actually does to floating and fixed mortgage rates.
-
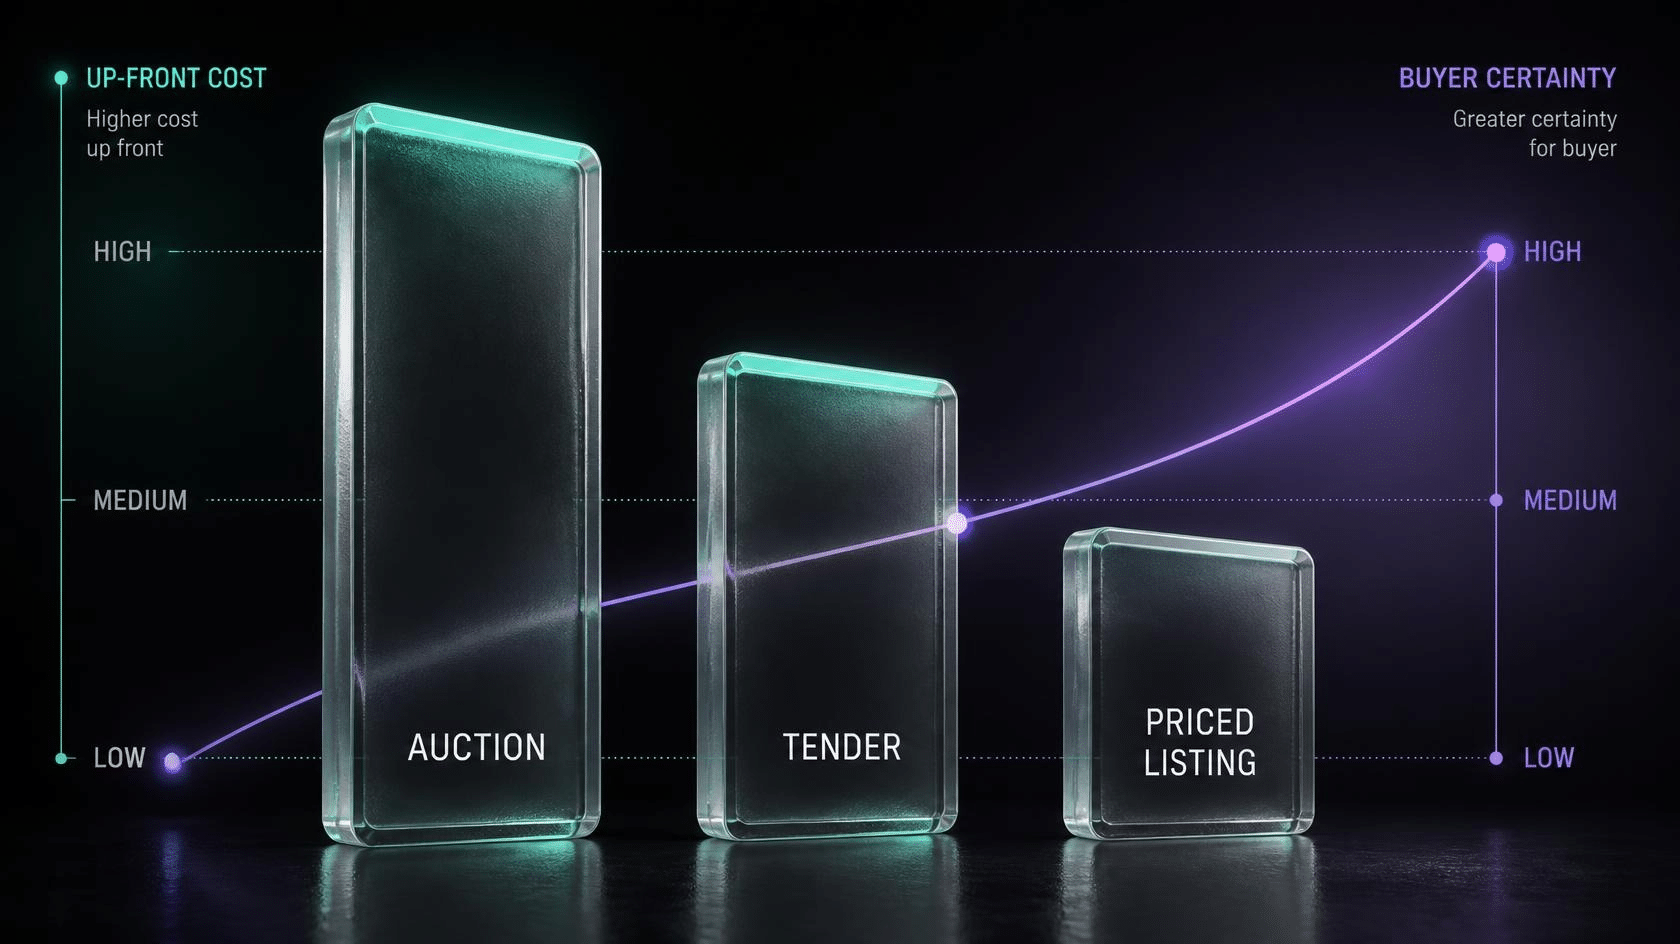
Auction, tender or multi-offer: how the sale method decides what you can offer
The sale method decides how much you have to spend before you know whether you have a house. Auctions are unconditional, tenders are one shot, multi-offers are blind. Here is what each one costs you up front.
-
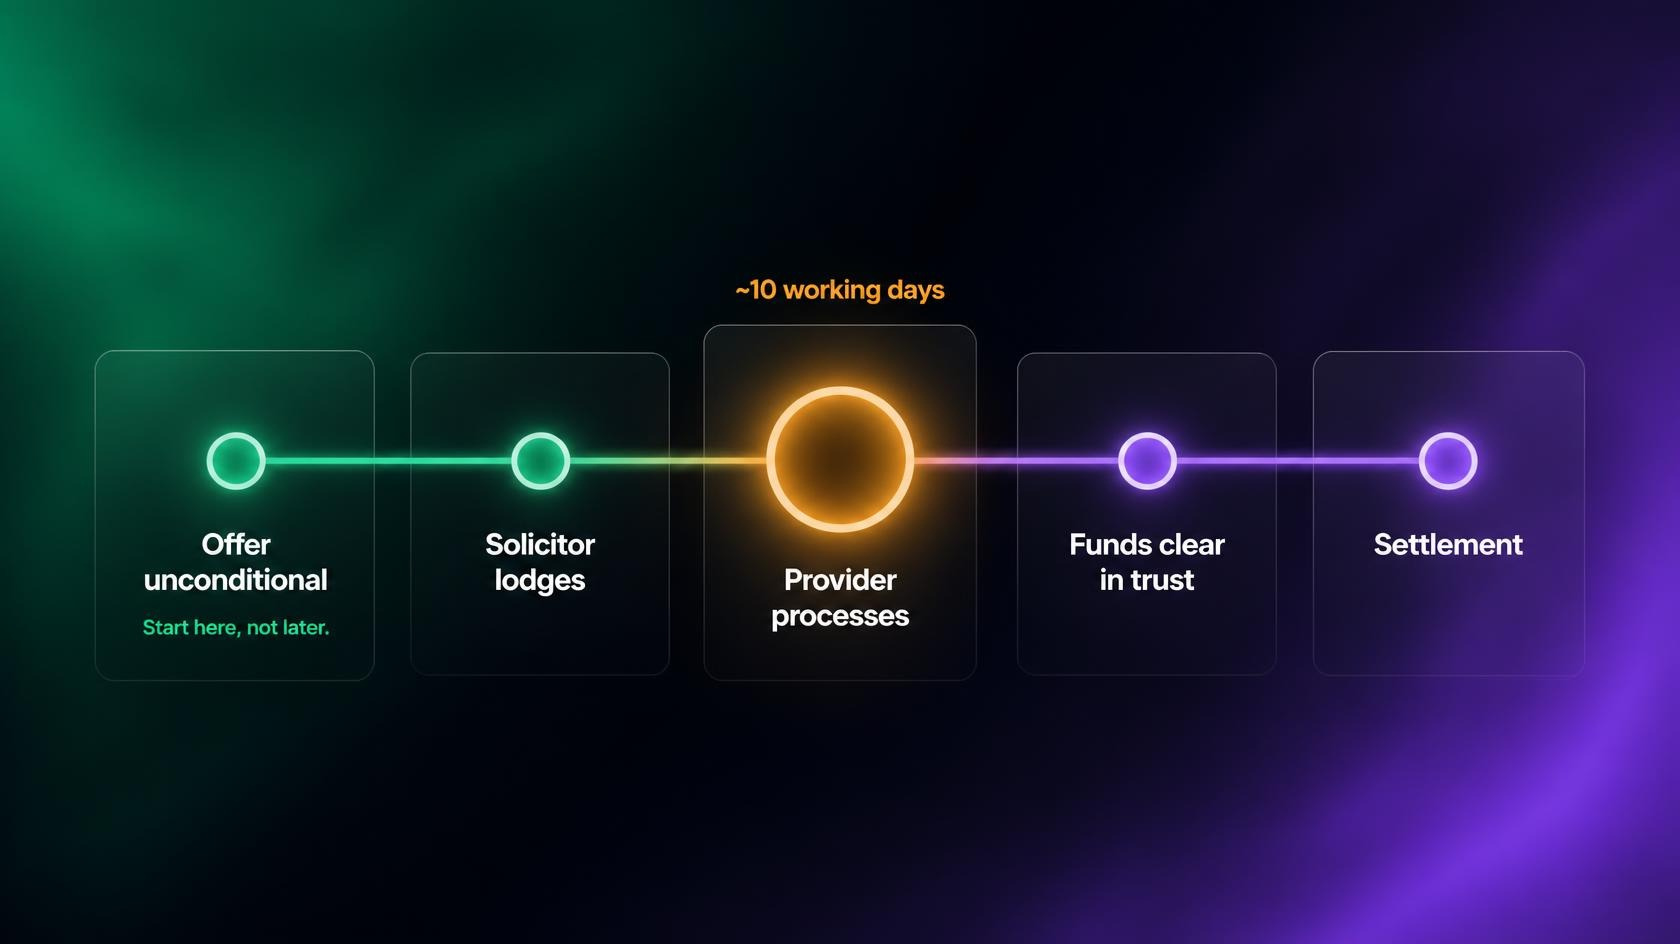
Your offer got accepted. What happens now?
Your offer being accepted starts a clock, commonly ten working days, in which you have to satisfy every condition written into the agreement. Nothing is binding yet. Here is the order to run finance, builders report, LIM and title in, and what actually goes wrong.
-
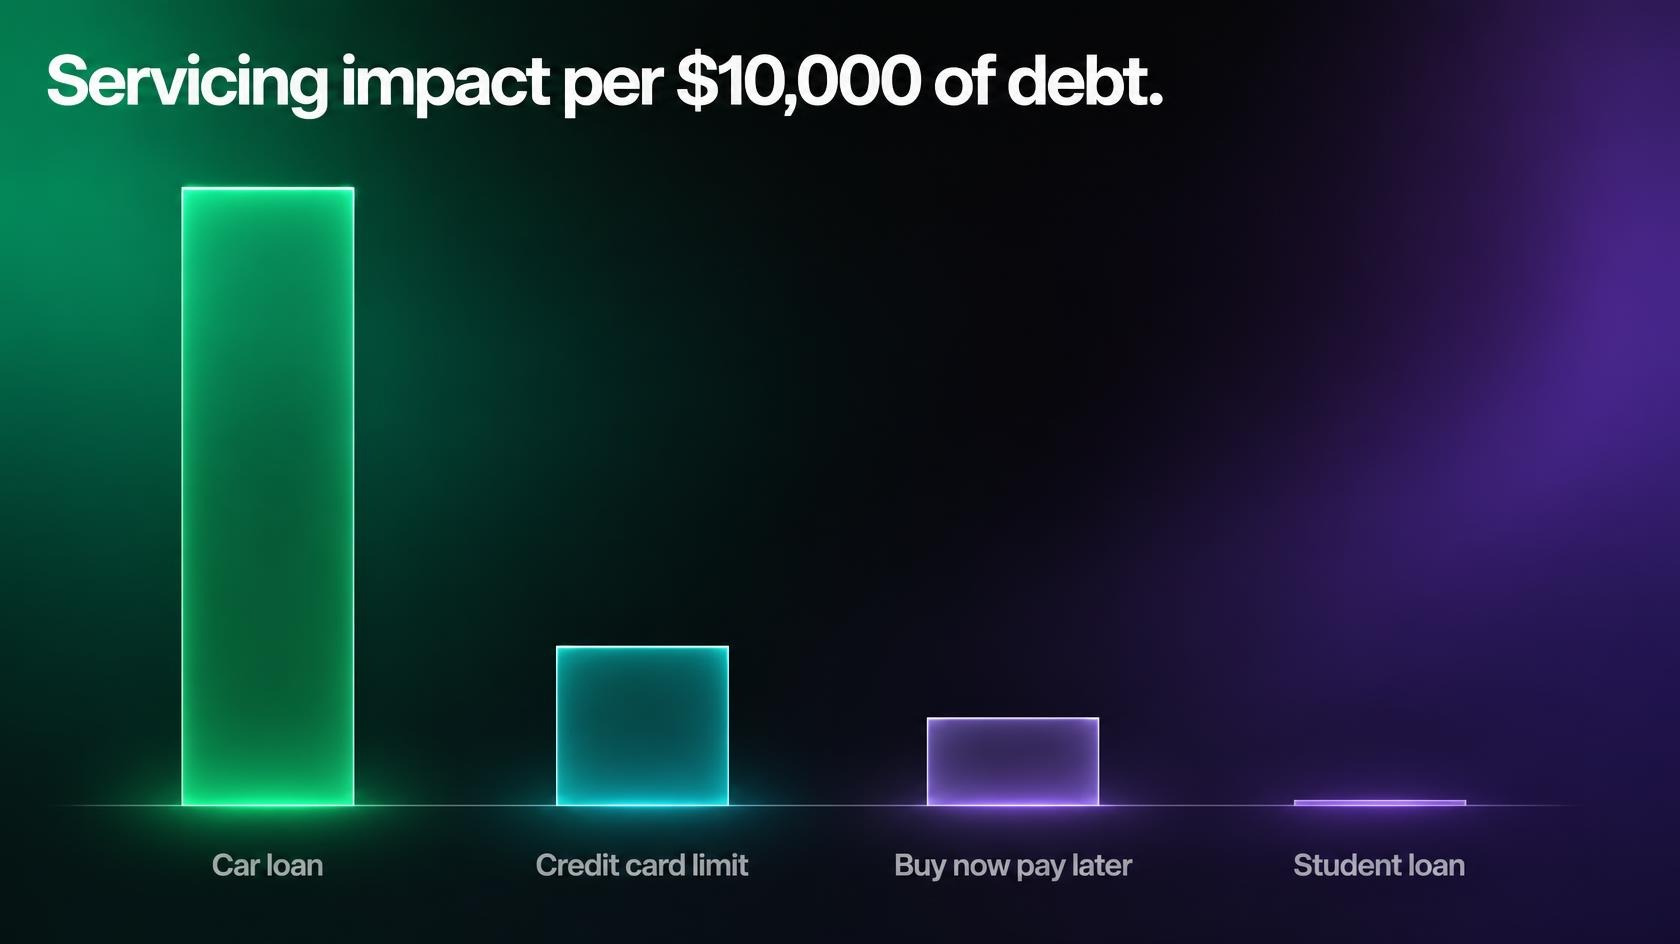
How credit cards, Afterpay and car loans affect what you can borrow
Banks do not assess your debts on what you pay each month. They assess them on what you could be forced to pay. Here is how New Zealand lenders treat credit card limits, buy now pay later, car loans and student loans, and which ones are actually worth clearing before you apply.
-
Using KiwiSaver for your first home
You can withdraw almost all of your KiwiSaver towards a first home if you have been a member for three years and will live in the property. You must leave 1,000 dollars behind. Here is what the money can pay for, when it arrives, and the ownership situations that quietly disqualify people.
-
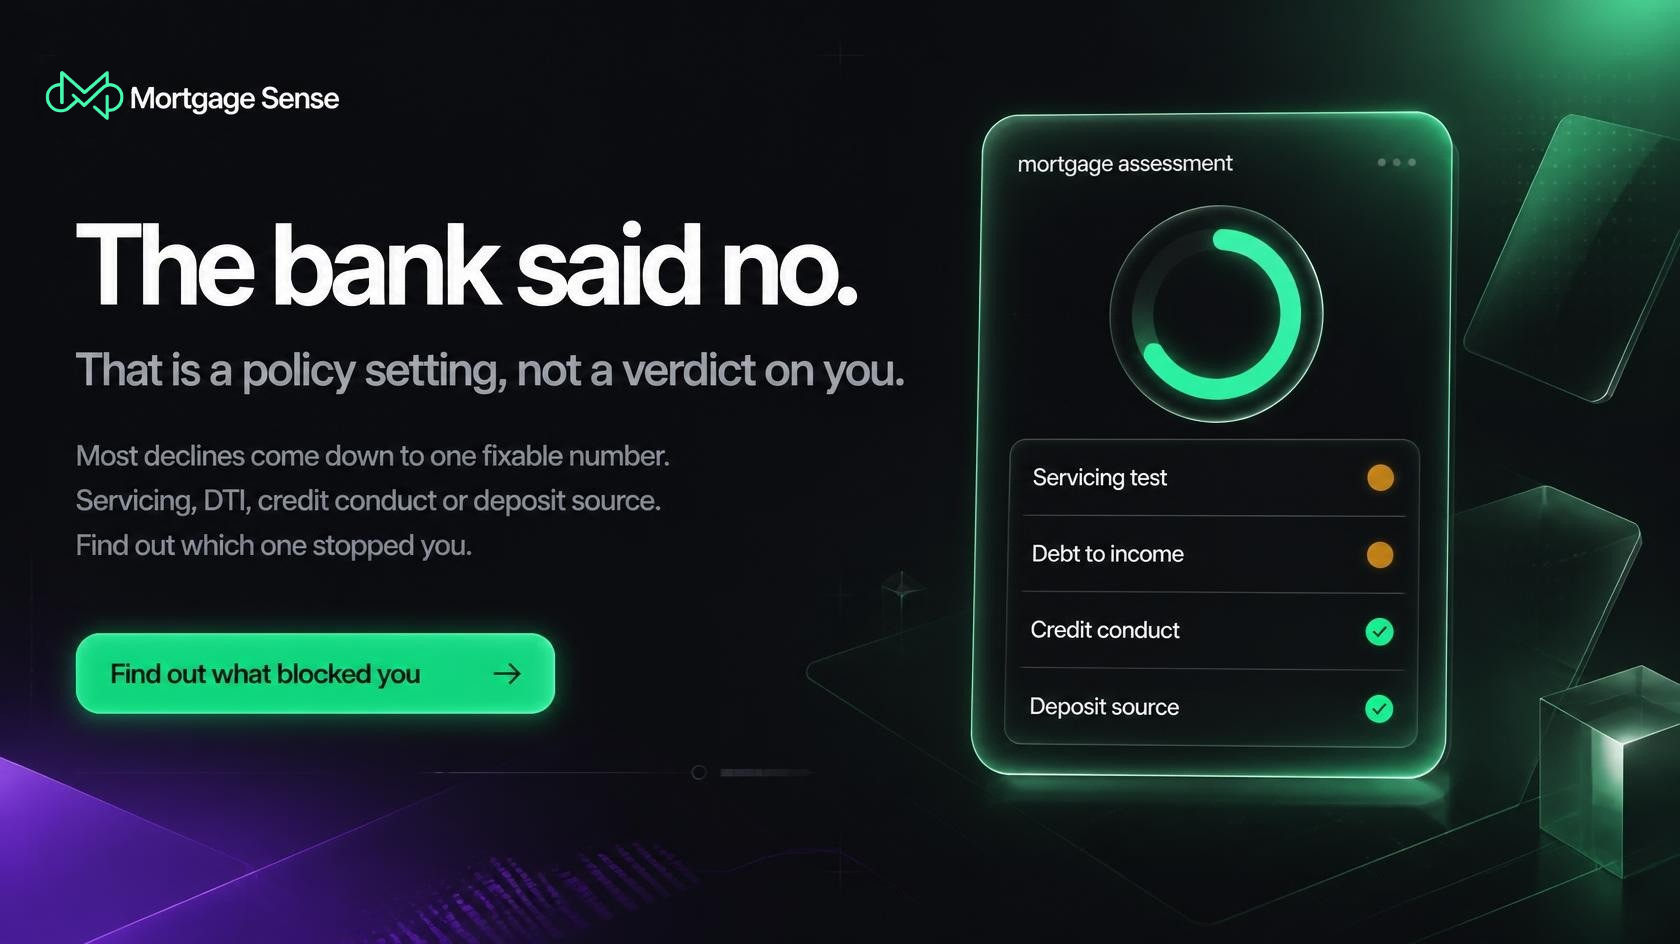
Home loan declined in NZ? Here is what actually blocked your application
Declined for a mortgage in New Zealand? A decline usually comes down to one part of the assessment rather than the whole application. What the common blockers are, how to work out which one applied to you, and what tends to move each.
-
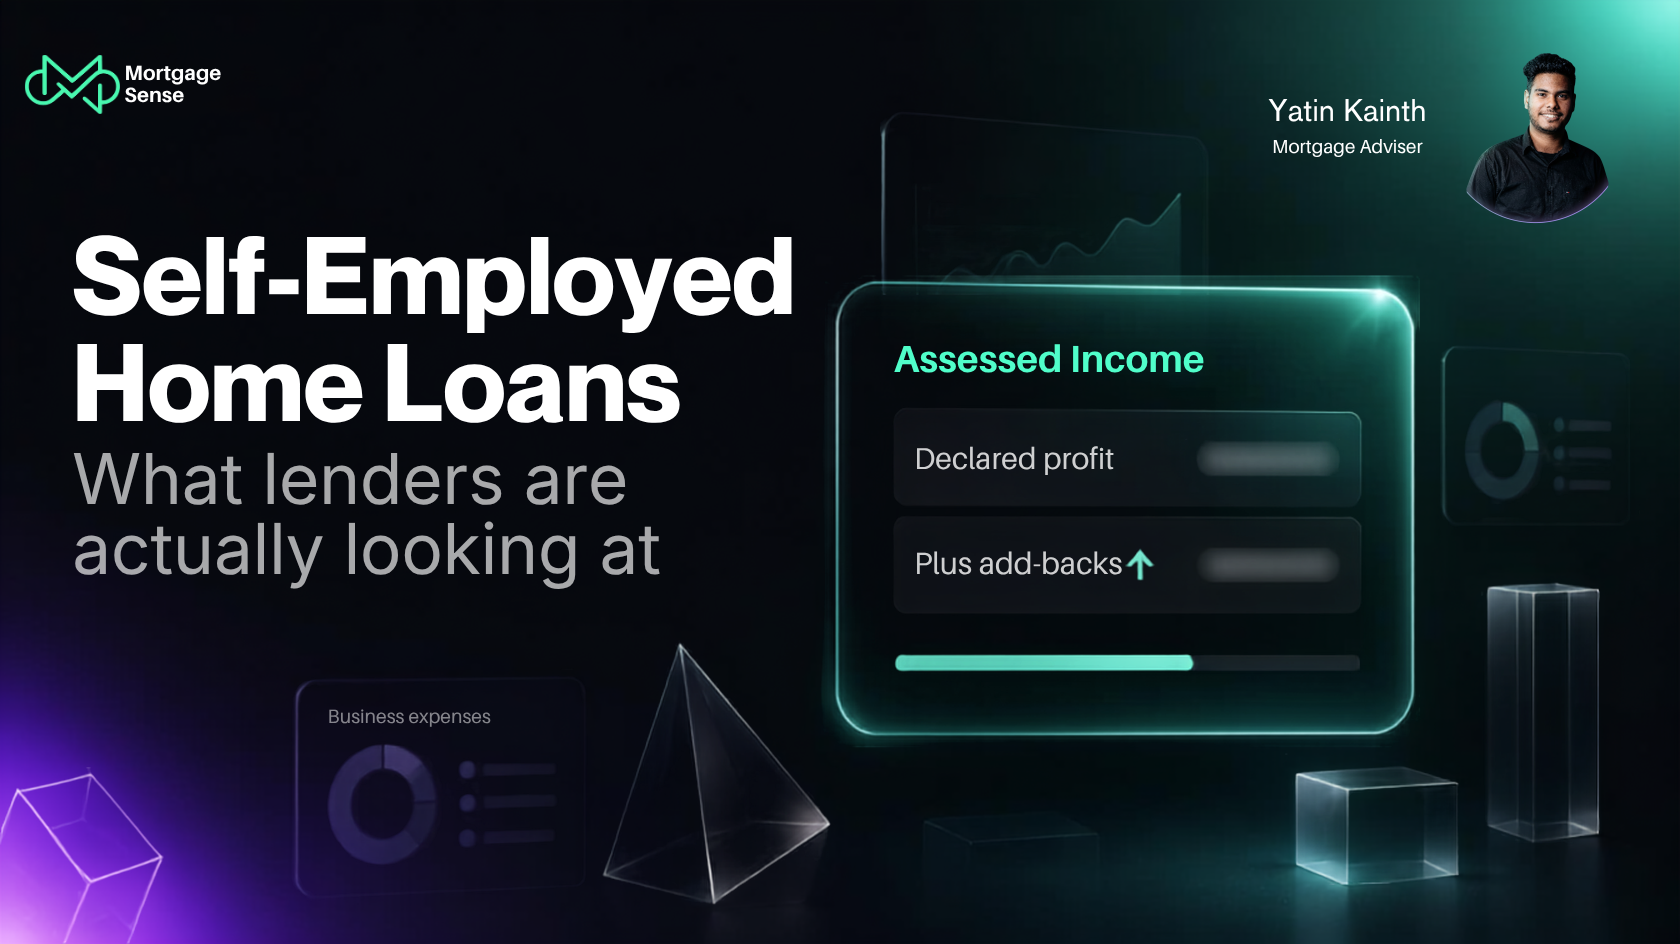
Self-employed home loans in New Zealand: what lenders are actually looking at
Written and reviewed by Yatin Kainth, Financial Adviser FSP1007497 · Last reviewed 25 September 2026 Short answer: yes, you can get a home loan in New Zealand when you’re self-employed, and if your income is fully documented a main bank will usually price you on the same rate card as a salaried borrower. What changes…
-

Can You Buy an Auckland Investment Property With Less Than a 20% Deposit?
Wondering if you can buy an Auckland investment property with under 20% deposit? Here’s what the LVR rules, new-build exemptions and lenders actually allow.
-
First Home Buyers Rejoice: ASB’s New 5% Deposit Home Loan Option
ASB now offers home loans with just a 5% deposit for eligible first home buyers. Here’s how it works, who qualifies, and what to watch for. Subject to lender assessment and approval criteria.
-

How First Home Buyers Can Navigate the New Zealand Loan Market
A practical guide for first home buyers navigating the NZ mortgage market — deposits, pre-approval, lender criteria and what to expect at each step. Indicative only; subject to lender assessment.