From Pre-Approval to Settlement: What Actually Happens After You Find a House?
Last reviewed: 9 October 2026. Condition periods, council timeframes and lender policies vary, so treat the timings here as typical rather than fixed and confirm dates with your lawyer.
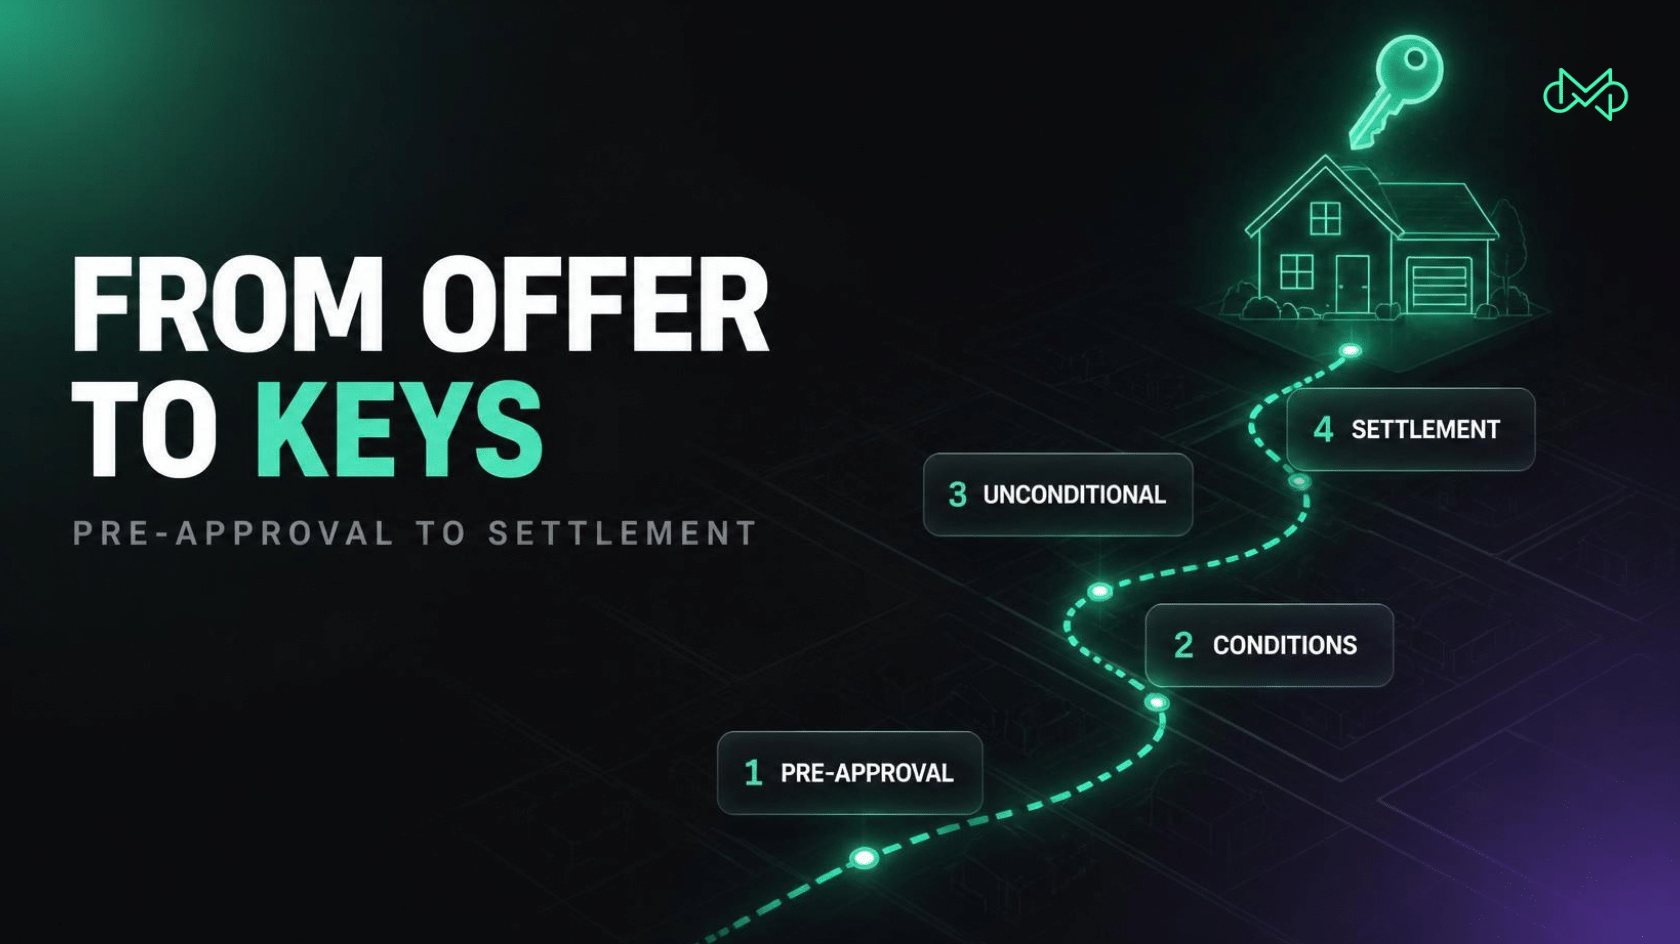
From pre-approval to the keys, it runs in this order: pre-approval, offer, condition period, unconditional, loan documents and insurance, pre-settlement inspection, settlement day. The condition period is where most things go wrong, so most of this page is about that. The rest covers what happens on either side of it.
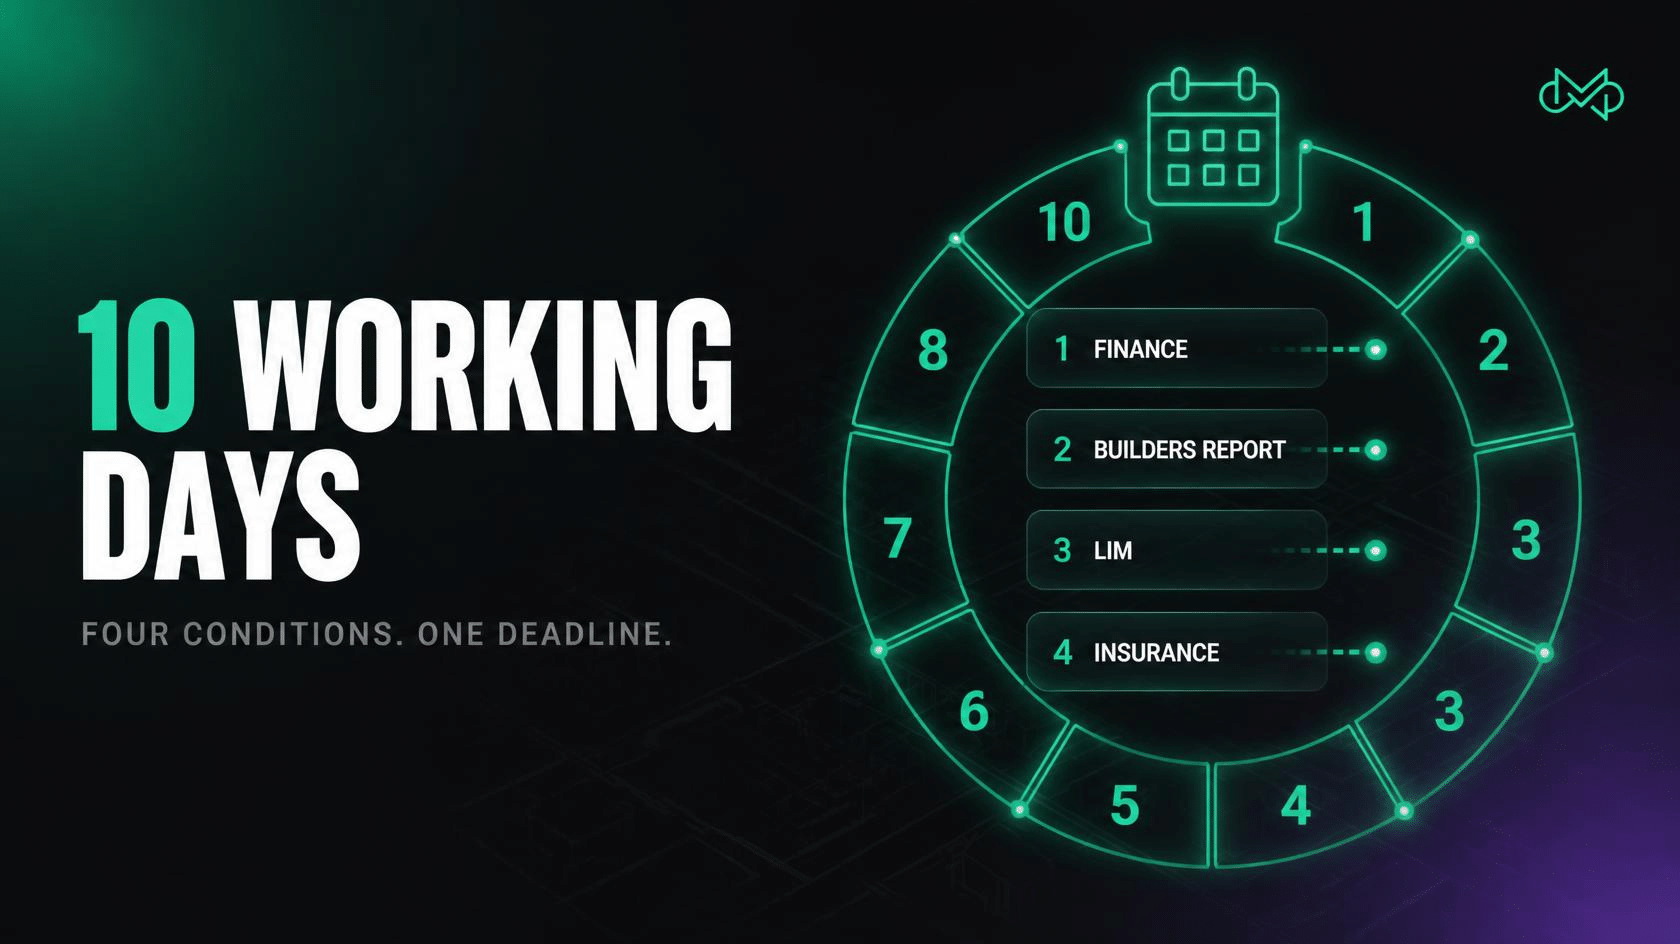
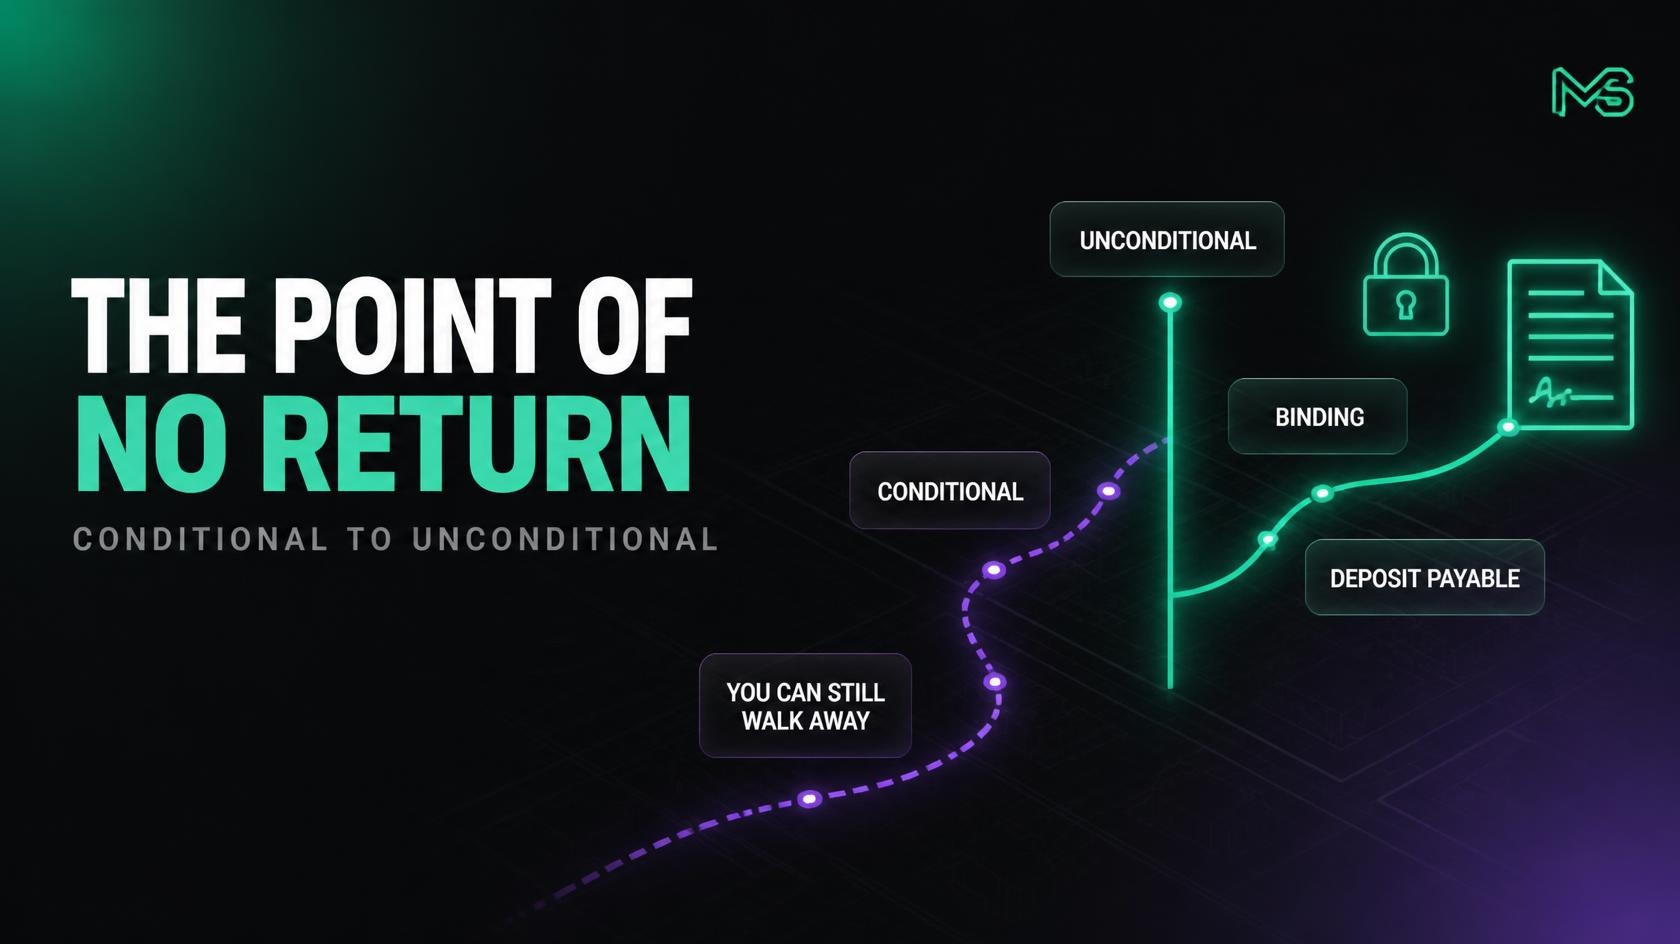
Your offer being accepted starts a clock, commonly ten working days, in which you have to satisfy every condition written into the agreement. Nothing is binding yet. Miss the date without an extension and the agreement can be cancelled. Confirm everything and you go unconditional, at which point you are committed and the deposit is payable.
Ten working days is not two weeks. With a public holiday in the middle it can stretch past a fortnight on the calendar. People book a builders report for day nine and find the inspector is not free until day fourteen.
Before you find a house: what pre-approval does
A pre-approval tells you roughly what a bank will lend you, on conditions. At the main banks it usually lasts about 90 days, and it can normally be extended if nothing has changed. It’s the bank approving you. It hasn’t seen the house yet, and that’s why finance is still a condition when you make an offer.
Three things quietly break pre-approvals: a change of job, new debt (including a car on finance or a new phone plan), and the bank’s view of the property itself. If any of those are coming, tell your adviser before you make an offer, not after. If your deposit is under 20%, expect the bank to want a registered valuation once you’ve found a place.
More on what it covers and what you’ll need: mortgage pre-approval in NZ.
| Stage | What happens | Who drives it | Typical timing |
|---|---|---|---|
| Pre-approval | Bank assesses you, not a property | You and your adviser | Lasts about 90 days |
| Offer accepted | Signed agreement goes to your lawyer and adviser | You | Day 0 |
| Condition period | Finance, builder’s report, LIM, title, insurance | You, lawyer, adviser | Set in the agreement, often 10 working days |
| Unconditional | Agreement is binding, deposit is paid | Your lawyer | End of the condition period |
| Loan documents | Bank issues the loan contract, you sign with your lawyer | Bank, lawyer | Between unconditional and settlement |
| KiwiSaver and insurance | Withdrawal lodged, insurance certificate sent to the bank | Lawyer, you | Start straight away. Providers need about 10 working days |
| Pre-settlement inspection | You check the house is as agreed | You, with the agent | A few days before settlement |
| Settlement day | Money moves, keys released | Lawyers | The date in the agreement |
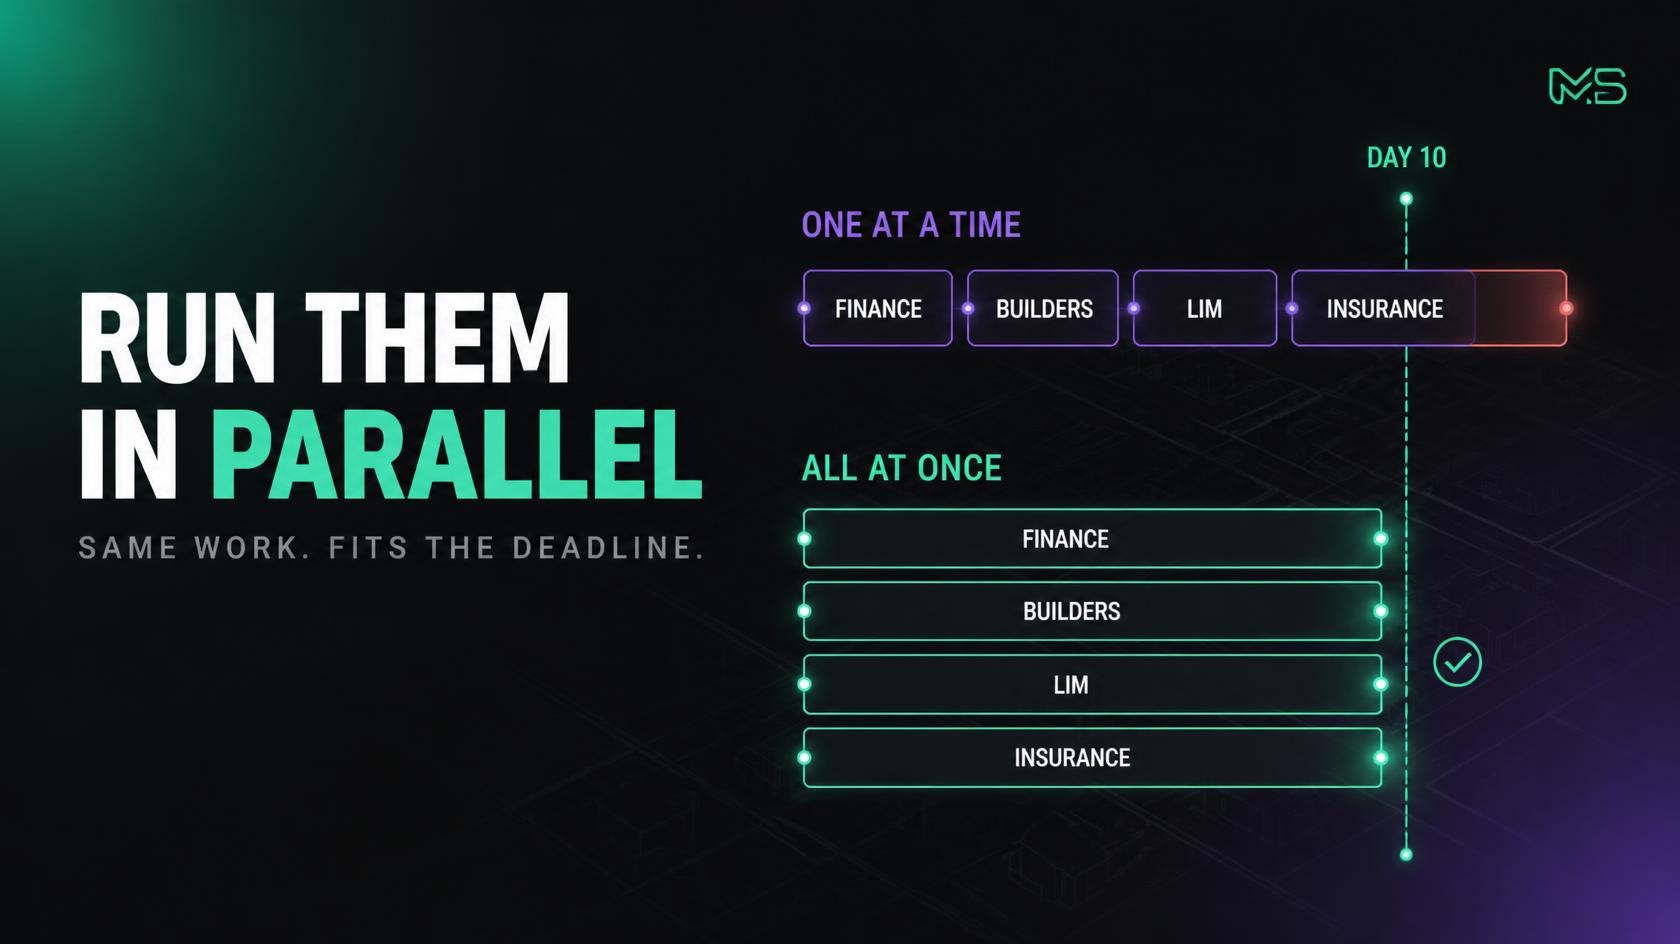
Run every condition at once
The most common mistake is doing conditions in sequence. Someone waits for the builders report to come back clean before bothering the bank, loses four days, then spends the last afternoon calling a lawyer who is already in a meeting.
They run in parallel. All of them, the morning after the offer is accepted. Your lawyer and your adviser both need the signed agreement on day zero, not a photo of the first page.
| Day | What should be happening |
|---|---|
| 0 | Offer accepted. Signed agreement goes to your adviser and your lawyer the same day. |
| 1 | Building inspection booked. LIM ordered. Adviser submits the full application with the property attached. |
| 2 to 4 | Lawyer reviews title, LIM and the agreement. Inspector attends. Insurance cover confirmed as available. |
| 5 to 7 | Building report back. Bank approves, or comes back with conditions of its own. Valuation ordered if the lender wants one. |
| 8 to 9 | Anything unresolved goes back to the agent now. Extension requested in writing if you need one. |
| 10 | Lawyer confirms conditions in writing. You are unconditional and the deposit is payable. |
Condition periods are counted in working days, so weekends and public holidays do not count. Write the actual calendar date down and confirm it with your lawyer, because this is where most of the panic comes from.
What each condition actually is
Finance. Your pre-approval is not finance approval on this house. The bank approved you. It has not approved this property. A pre-approval can be live and correct and the bank can still decline a particular place because of the title, the size, the condition, or a valuation that comes back short.
Builders report. Usually worded as a report satisfactory to the purchaser, which gives you room to walk if it comes back badly. The wording matters, and your lawyer should see it before you sign rather than after.
LIM. The council file on the property. Consents, drainage, hazards, notices. Councils take several working days in most districts and longer in some, which is exactly why this gets ordered on day one.
Title and solicitor’s approval. Your lawyer reads the title, the easements, the covenants, and the lease documents if it is cross-lease or unit title. If something on the title is a problem, this is the condition that lets you out.
Insurance. Overlooked until the bank asks for a certificate. If the house has had a fire, sits in a flood zone, is partly unconsented, or is pre-1940 with original wiring, cover is not automatic and it can take longer than you expect.
Not sure your pre-approval covers this property?
Send through the listing and the agreement. We will tell you quickly whether the lender is likely to have a problem with it.
Can I pull out before unconditional?
Only through a condition, and only on the grounds that condition gives you. Changing your mind is not a finance decline. If you cancel without a proper basis the vendor can pursue you, and losing the deposit is the least of it.
Worth saying plainly, because a lot of buyers treat the condition period as a free trial. It is not. It is a window to check specific things, and each condition only lets you exit for its own reason.
Going unconditional means the agreement is binding. Do not confirm a condition you have not actually satisfied, even under pressure from an agent, and never confirm finance before your adviser has written approval on that address.
Extensions are normal. Silence is not.
Councils run late. Inspectors get booked out. Banks ask for one more payslip on day eight. Extensions get granted all the time, and most vendors would rather grant one than watch the deal collapse.
What kills agreements is going quiet. If something is not going to land, the request goes through your lawyer to the vendor’s lawyer, in writing, before the deadline. Not at ten to five on the day.
The worst version of this is a buyer who cannot reach their own lawyer on the afternoon of the deadline and has no idea whether they still have the house. If you cannot get hold of your lawyer, call the agent and get the extension moving rather than waiting for a callback.
Conditions the bank adds after approval
This one catches people. The bank approves the loan and then attaches its own conditions to settlement, separate from the ones in your agreement. The usual ones: close a named credit card, provide a boarder declaration, show evidence a debt has been repaid, supply the insurance certificate, accept a registered valuation.
None of those are refusals. They are things to work through. But they have to clear before drawdown, and the ones involving somebody else take longer than the ones involving you.
Worth reading alongside this: buying at auction in NZ, tenders and multi-offers, how much can I borrow, using KiwiSaver for your first home, and what to do if your home loan is declined.
After unconditional: the road to settlement
Once you’re unconditional, the pressure drops, but there’s still a list. Most of it runs through your lawyer. Your job is to answer quickly and not change anything about your finances.
The deposit
If it wasn’t paid when you signed, the deposit is normally due when you go unconditional. Around 10% is common, but it’s negotiable. If any of it is coming from KiwiSaver, sort out with your lawyer before you sign how that will work.
Loan documents
The bank sends your loan documents to your lawyer, who goes through them with you before you sign. Read the rate, the term and the split between fixed and floating. If something doesn’t match what you agreed, now is the time to say so, not the week of settlement.
Insurance
The bank won’t release the money until it has a house insurance certificate that notes the bank as an interested party. Arrange cover to start on settlement day, and send the certificate to your adviser or lawyer as soon as you have it.
Your KiwiSaver withdrawal
Your lawyer lodges it with your provider using the signed agreement. Allow about 10 working days, sometimes more. It can’t be paid out after settlement, so this one can’t slide. The full rules are in using KiwiSaver for your first home.
Don’t change anything
No new car loan, no new credit card, no job change. The bank can recheck before it releases the money, and I have seen settlements wobble because someone bought a car on finance the week before.
The pre-settlement inspection
You’re entitled to inspect the property before settlement to check it’s in the condition you agreed to, with the chattels that were listed. Do it a couple of working days out so there’s time to fix anything. Run the taps, try the oven, open the garage door.
Settlement day
On the day, your lawyer pays the vendor’s lawyer using your deposit, your KiwiSaver and the bank’s money. Once the vendor’s lawyer confirms the funds have arrived, the agent releases the keys. That’s usually some time in the afternoon, so don’t book the movers for 8am.
If settlement runs late on your side, you can be charged default interest for each day it’s late. If it runs late on the vendor’s side, your lawyer will deal with it. Either way, stay reachable on settlement day.
Found a place, or about to?
Do the quick assessment and tell me where you’re at. I’ll check your pre-approval still fits, and line up the bank, valuation and insurance so the condition period doesn’t catch you out.
Takes about two minutes. Rather talk? Book a free chat or call 022 064 7770.
Frequently asked questions
Commonly ten working days, though anything from five to twenty gets written in. It is negotiable when you make the offer, so if you know your bank is slow, ask for longer up front rather than requesting an extension later.
Working days. Weekends and public holidays do not count, which is why the actual calendar date is the thing to write down and confirm with your lawyer.
Usually. A deposit of around 10 percent is common, though it’s negotiable, and it’s often due when you go unconditional. KiwiSaver can go towards the deposit if a stakeholder holds it until settlement, but it can’t be used for an auction deposit, and the paperwork takes time. Agree how the deposit will be paid with your lawyer before you sign.
Yes. Tell your adviser before you make an offer rather than after. Renewing usually needs fresh payslips and statements, and it takes days rather than minutes.
Not on your own. Both parties have to agree to a variation, so the conditions need to be right before you sign.
The deposit is payable, the agreement is binding, and the next date that matters is settlement. Your lawyer takes over most of the running from there.
It depends on the dates in your agreement. The condition period is often around 10 working days, and settlement is whatever date you and the vendor agree. Pre-approval itself usually lasts about 90 days while you look.
Your lawyer pays the vendor’s lawyer with your deposit, any KiwiSaver and the bank’s money. Once the funds are confirmed, the agent releases the keys, usually in the afternoon.
Yes. You’re entitled to a pre-settlement inspection to check the property and chattels are as agreed. Doing it a couple of working days before settlement gives time to fix any problems.
Signed loan documents, a house insurance certificate noting the bank, a valuation if it asked for one, and anything it listed as a condition of approval, such as closing a credit card.
Sources and further reading
- Real Estate Authority, Buying a property, sale and purchase agreements
- New Zealand Law Society, Buying and selling property
- Consumer Protection, Buying a home
- Settled.govt.nz, Understanding the sale and purchase agreement
- Inland Revenue, KiwiSaver first home withdrawal
Working through a condition period right now?
If the clock is already running and something is not moving, send it through. We will tell you where it actually sits and what to chase first.
This article is general information only and not personalised financial advice. It does not take account of your objectives, situation or needs. Details of our services and fees are set out in our Disclosure Statement. You can also read how we are paid, how to make a complaint and our Privacy Policy.
Ready to talk it through?
Get mortgage advice NZ homeowners actually trust. Book a free, no-pressure chat with Yatin.
Book a free chat →