Refinance Your Mortgage in NZ Check the numbers before you switch
Refinance your mortgage in NZ if a different lender, rate or loan structure could suit you better. A home loan mortgage refinance means moving your home loan to a new lender, or restructuring it with your current one, to lower the cost, access equity or consolidate debt. Savings are not guaranteed.
We compare 30+ lenders. Use the estimator below, then book a free review and we will check the break fee, switching costs and cashback clawback before you decide. New to this? Read how to refinance a mortgage, step by step.
Access to 30+ LendersNo Cost to Most Borrowers*NZ-Wide ServicePersonal Mortgage AdviserCompetitive Rate Comparison
Why Now Might Be the Right Time to Refinance Your Mortgage
Refinancing your mortgage is easier than many homeowners think. The mortgage landscape changes constantly. Importantly, even if you haven’t switched lenders recently, your refinancing opportunities may have improved significantly — and you might not realise it.
📋 Lending Policies Shift
Notably, lenders update their serviceability rules and assessment criteria regularly. As a result, a lender that said no two years ago might say yes today.
📈 Property Values Increase
Over time, your home builds equity. In effect, that equity is an asset — and refinancing lets you access it for renovations, investments, or debt consolidation.
💼 Your Finances Improve
Salary increases, improved credit scores, and career advancement change your borrowing capacity. Consequently, better finances often unlock better lending terms.
The only way to know whether refinancing makes sense is to get a professional assessment.
How Refinancing Your Home Loan Can Strengthen Your Financial Position
When you refinance your mortgage, you have multiple options. Here’s what’s possible: Here are the main reasons homeowners refinance — and how each one can work for your situation.
Key Reasons to Refinance Your Mortgage
📉
Lower Your Mortgage Interest Rate
Even a small rate drop compounds significantly over decades. Therefore, we compare 30+ lenders to find your best available rate.
💰
Improve Cashflow
Monthly savings of $300–$500 can make a real difference to cashflow. In turn, that freed-up income funds your priorities.
🏠
Access Your Mortgage Equity
For instance, you can use released equity for renovations, investment, education, or debt consolidation at more favourable rates than personal loans. Refinancing is also a good time to add a revolving credit or offset account to your loan structure.
⚠️ Borrowing against equity increases your secured debt. Professional advice ensures responsible equity use.
🔄
Refinance to Consolidate Debt
Essentially, you roll high-interest personal loans and credit cards into your mortgage at a more favourable rate. As a result, you have one payment and one lender.
First Home Buyers → Consolidation can improve affordability if you have existing debt.
🔨
Fund Renovations
Generally, mortgage lending offers better rates than specialty renovation finance. Ultimately, you improve your home at competitive cost.
📊
Invest in Property
Refinance your primary residence to release equity for your next investment purchase.
For example, you can switch IO to P&I, split your loan for flexibility, set up an offset mortgage, or adjust your term. Indeed, refinancing is the ideal time to reshape your strategy.
✨
Simplify Finances
Multiple mortgages scattered across lenders? Consolidate into one loan, one payment, one relationship. Clarity builds confidence.
Eligibility
Refinance Mortgage Options for Different Situations
The good news: many homeowners may be eligible to refinance. Here’s how different situations are typically assessed.
💼
Refinancing for PAYE Employees
Generally, stable employment strengthens your application. As such, refinancing is often faster for PAYE borrowers, subject to lender assessment.
💻
Refinancing for Self-Employed Borrowers
Admittedly, more documentation is required (tax returns, GST, P&L). However, many self-employed borrowers refinance successfully.
Self-Employed → Detailed guidance on self-employed refinancing.
🏘️
Property Investors & Portfolio Owners
Similarly, investment properties refinance regularly. We know which lenders specialise in investor portfolios.
Unique circumstances are exactly when professional guidance helps most. Get in touch for an individual assessment.
The Process
Most refinances need a fresh value on your home. Read property valuation NZ to see which type the new lender will want.
How the Refinance Process Works
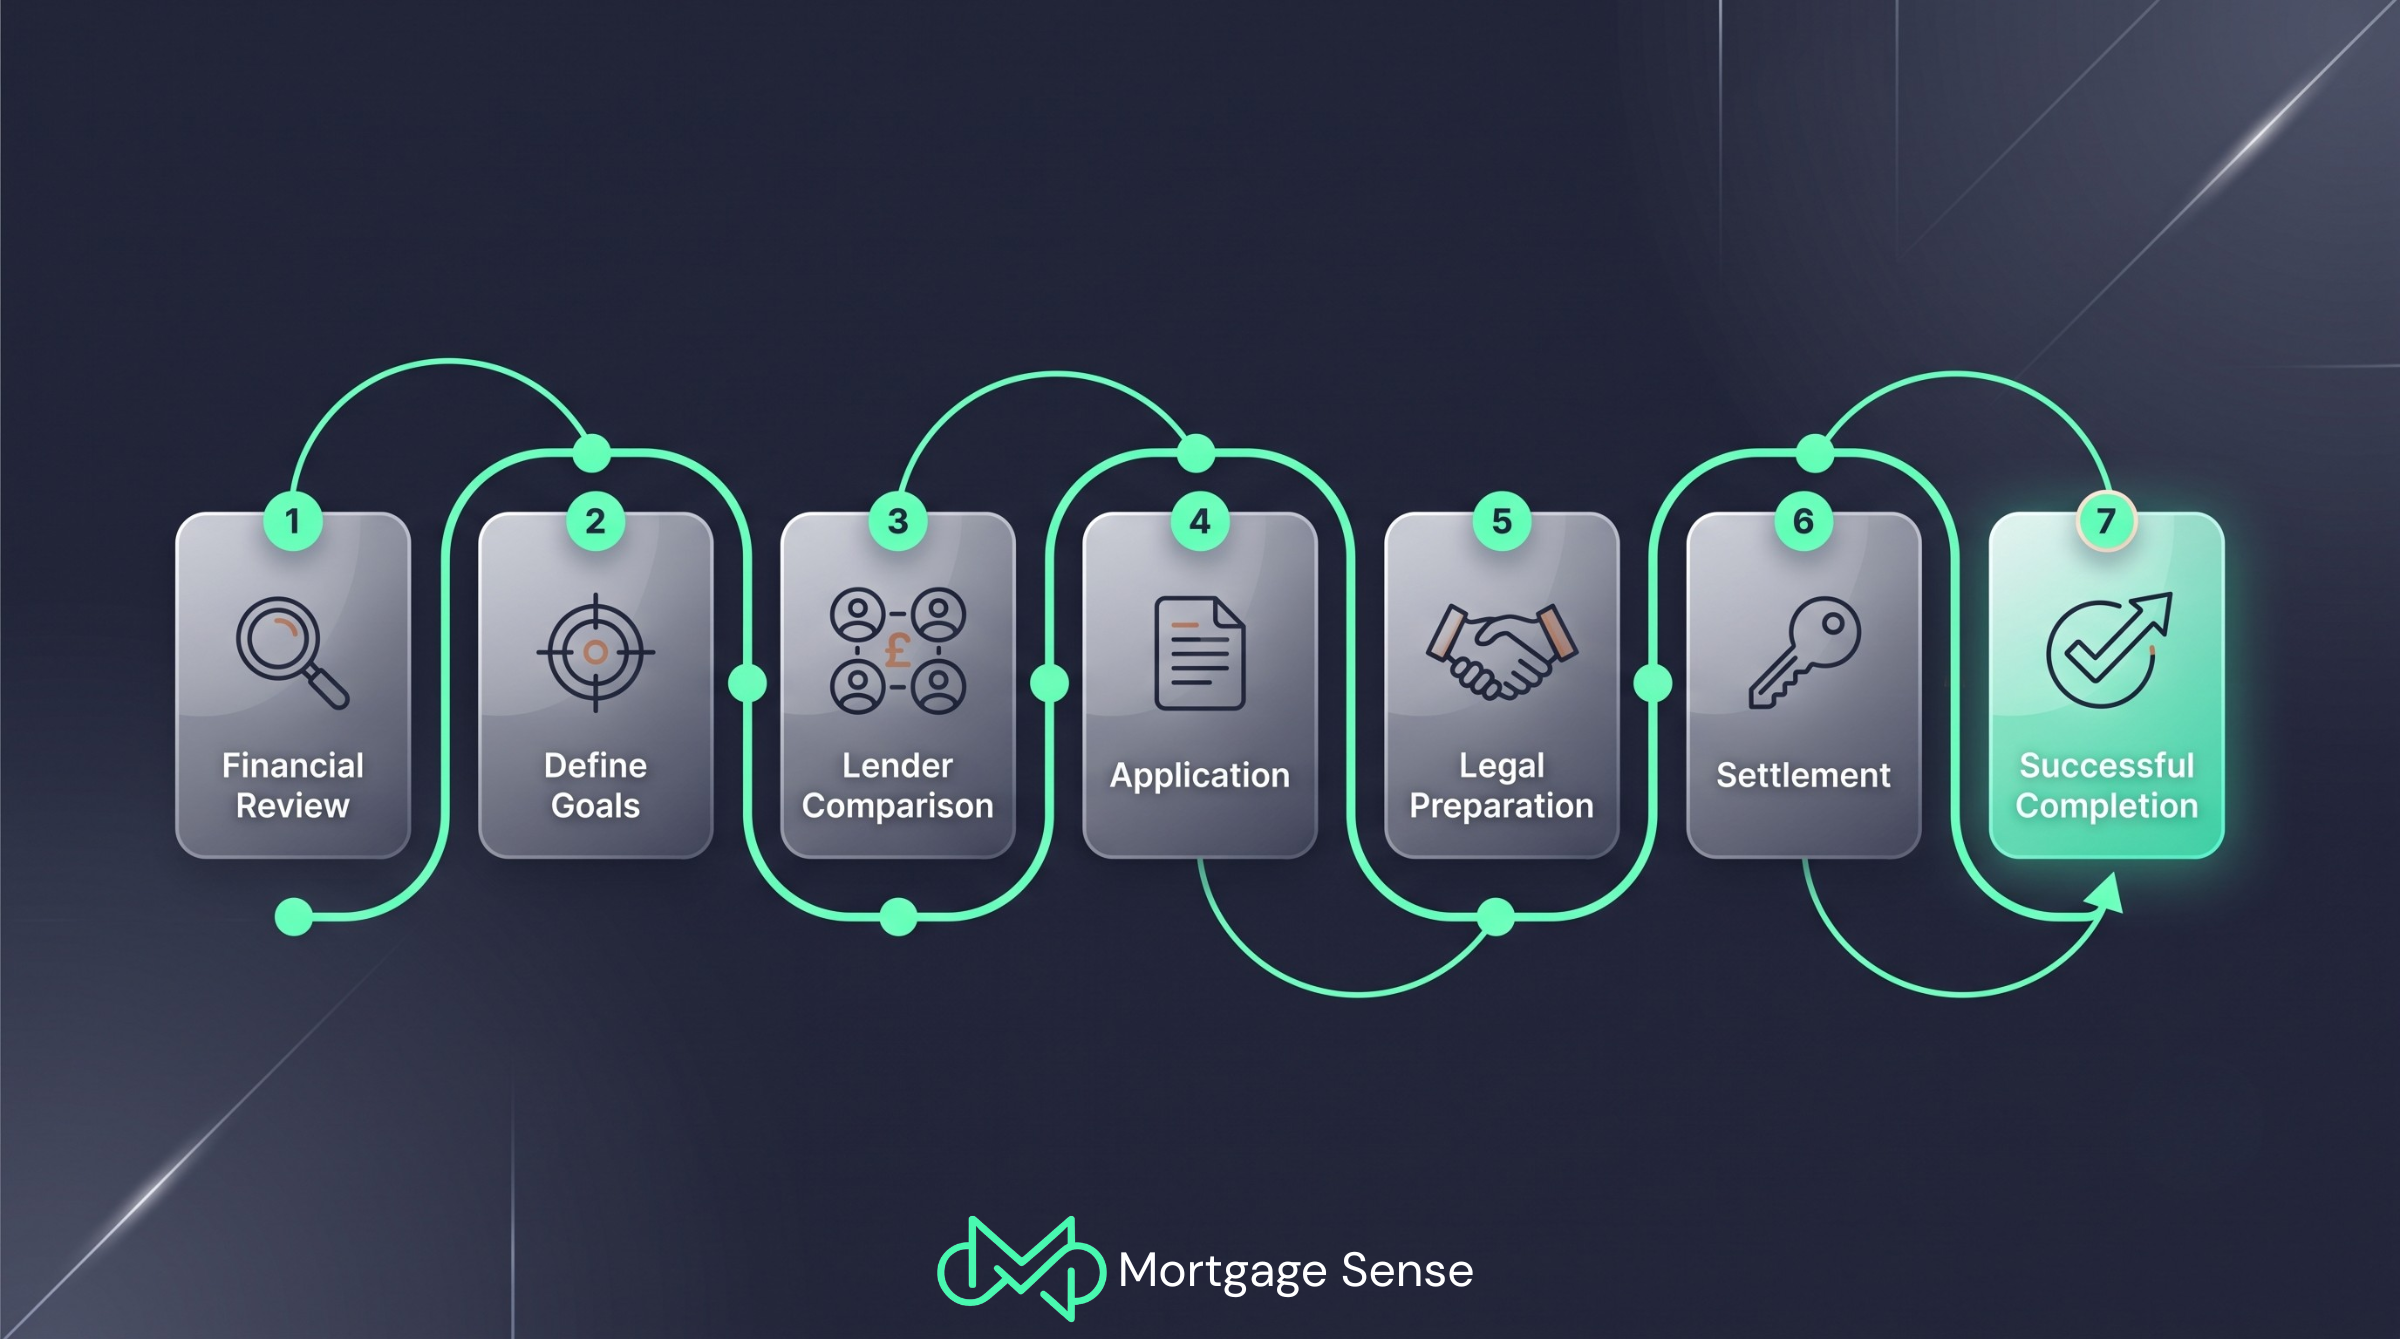
The short version. The full walk-through is in our step-by-step guide.
In short: we review your current loan and goals, send the application to the most suitable lenders, work through conditional approval, then your lawyer arranges the discharge of the old mortgage and the new lender pays it out at settlement. I’d start four to six weeks before your fixed term ends. Timing depends on the lender and how quickly your documents arrive.
When Should You Refinance Your Mortgage? Key Scenarios
Rates Have Dropped
If your current rate is 1% or more above market rates, refinancing usually makes financial sense. Calculate savings minus costs to confirm net benefit.
To compare your current rate against real offers, get a mortgage quote.
You’ve Built Equity
20%+ equity unlocks genuine refinancing benefits. Access cash at better rates than personal loans or credit cards — if you’ll use it wisely.
High-Interest Debt
Consolidating into your mortgage at a more favourable rate often makes sense — if you commit to not re-accumulating the debt.
Income Has Improved
A salary increase lets you afford higher repayments. Refinancing to a shorter term builds equity faster and reduces total interest paid.
Switching Loan Structure
IO period ending, or want to split your loan? Refinancing lets you restructure to match your goals. Plan ahead for repayment changes.
Circumstances Changed
Improved credit, bonus, promotion? Better circumstances often unlock better lending terms. A review confirms what’s now possible.
⚠️ When to hold tight: Refinancing costs exceed savings over your remaining loan term · You’re close to paying off your current loan · Planning to sell within 2–3 years · Breaking a fixed rate would incur significant penalties.
Debt Consolidation
Using Refinancing to Consolidate Debt
Additionally, refinancing is often the perfect time to consolidate personal loans, credit cards, or vehicle loans into your mortgage. Here is a worked example of consolidating debt into your mortgage.
What can be consolidated?
Personal loans, credit cards, vehicle loans, and BNPL debt can all be consolidated when you refinance.
Why it works
Notably, mortgage lending carries significantly lower interest rates than unsecured debt. As a result, you get one payment, greater clarity, and faster payoff.
⚠️ Critical risks
Crucially, you’re converting unsecured debt into a secured debt — meaning your home becomes security. Without addressing spending habits, you’ll re-accumulate credit card debt while owing a larger mortgage.
Debt Consolidation → Deeper dive into consolidation strategies, risks, and alternatives.
Refinancing Scenarios
How Refinancing Can Work
The following refinance mortgage examples are illustrative and based on common NZ scenarios. Individual results vary. Subject to lender assessment and individual circumstances.
Auckland Family
Rate Reduction
Situation: Fixed rate expired; market conditions had improved roughly 1.5% below their existing rate.
Outcome: Refinanced successfully. Monthly repayments reduced materially. Total refinancing costs recovered in under 3 months. Substantial interest saved over the loan term.
Hamilton Business Owner
Equity Release & Expansion
Situation: Substantial equity across two properties; needed capital for an investment property without selling.
Outcome: Refinanced primary property to access equity. Restructured across two lenders. Investment property purchased. Portfolio expanded with separate securities maintained.
Christchurch Investor
Credit Card Debt Consolidated
Situation: Home loan plus high-interest credit card debt across multiple cards draining cashflow.
Outcome: Consolidated all credit card debt into mortgage at significantly more favourable rates. Single payment, materially improved cashflow, accelerated debt payoff.
Why Mortgage Sense
Why Homeowners Choose Mortgage Sense for Refinancing
🔍
Mortgage Refinancing Specialist Knowledge
NZ refinancing strategies, timing, lender policies and optimal structures — not just loan applications.
🏦
30+ Lenders
We compare across 30+ lenders to find you the best available terms for your situation.
📋
Transparent Costs
Every cost explained upfront. You know exactly what you’re paying and why — no surprises at settlement.
⚡
Fast Process
We streamline the refinancing process. Pre-approval in as little as 5–10 business days.
🤝
We Negotiate for You
We negotiate with lenders on your behalf, compare options, and help secure competitive terms. You focus on the decision.
🔄
Consolidation, Done Carefully
We assess whether consolidation is right for you, structure it correctly, and support you beyond settlement.
📅
Ongoing Support
After refinancing, we help plan future equity access, investment properties, or debt freedom. Relationship-based.
✅
Honest Advice
If refinancing doesn’t make sense for you, we’ll tell you honestly. Your long-term benefit is our priority.
Switching Banks
What Does Switching Banks Cost in NZ?
Switching banks usually makes sense when your fixed rate is ending and another lender offers a lower rate, a better loan structure or a cash contribution that outweighs the costs. Start looking about six weeks before your fixed term finishes so there’s time to compare offers, get approval and let the lawyers handle the switch.
Cost
When it applies
How to handle it
Break fee
Leaving a fixed rate before it ends, if wholesale rates have fallen
Time the move for the end of the fixed term, or check the saving still beats the fee. See how break fees are worked out
Cashback clawback
Leaving within the minimum period your current bank’s cash contribution requires
Check your loan documents for the date the clawback ends
Legal fees
Almost always, to discharge one mortgage and register another
Will Refinancing Your Mortgage Actually Save You Money?
Refinancing only makes sense if the interest savings outweigh the costs. Here’s how to think about it.
Upfront Costs (What You Pay)
Valuation$500–$1,200
Legal/conveyancing$1,200–$2,500
LIM report (if required)$250–$400
Total typical range$2,200–$4,600
If refinancing doesn’t make financial sense, we’ll tell you honestly. Your long-term benefit is our priority — not commission.
Illustrative Example: $500,000 Loan
Loan Amount
$500,000
↓
Rate Improvement
~1.2% reduction
↓
Est. Annual Saving
~$6,000
↓
Refinancing Costs
~$3,500
↓
Break-Even Point
~7 months
↓
Est. Long-Term Benefit
~$116,500
Indicative only. Your actual savings depend on rate available, costs, and remaining term.
Savings Calculator
Estimate Your Mortgage Refinancing Savings
Indicative only — actual savings depend on the rate available, refinancing costs, and your loan term.
Monthly Saving
—
Annual Saving
—
Lifetime Saving
—
Break-Even Period
—
Indicative only — not financial advice. For your personalised assessment, book a free review.
NZ Refinancing Guide
Key Terms & Timing for NZ Borrowers
Generally, with fixed-rate loans, you refinance when the fixed term ends — no break fees apply. By contrast, floating-rate loans can be refinanced anytime. If you have a hybrid loan (part fixed, part floating), each portion ends at a different time. Plan ahead — don’t wait until your fixed rate is about to expire.
If you refinance before your fixed rate expires, your lender charges a break fee — their cost of unwinding the interest rate swap they entered. Break fees can be substantial (sometimes significant five-figure amounts). The key question: Is the interest saving worth paying the break fee? We calculate this exactly during your assessment.
Ideally, we recommend reviewing every 12–24 months. In particular, the 6 months before your fixed rate expires is especially important. Triggers: rates drop, life changes, improved credit, built equity, changed circumstances. Annual review is the minimum good practice.
Essentially, refixing means fixing at a new rate before your current fixed term ends. Notably, most lenders allow this. It’s often used to lock in rates if you think they’ll rise further. Refixing can be combined with refinancing to a different lender.
Sometimes your existing lender can match competing offers, so switching may not be necessary. Conversely, other times switching provides greater value. Every situation is different. We compare both options so you can make an informed decision based on your specific circumstances.
To refinance a mortgage is to replace your existing home loan with a new one, either with a different lender or by restructuring with your current lender. People do it to change the rate or loan structure, access equity or consolidate debt. At settlement the new loan pays out the old one.
Yes. The new lender assesses your income, spending, credit and the property, and your lawyer arranges the discharge of the old mortgage. Approval is never guaranteed. Our guide to how to refinance a mortgage covers each step.
It can be, but cashback is usually clawed back if you leave within the lender’s minimum period, so you are signing up to stay. Compare the cashback, the rate and the loan features together, and check the current terms with the lender.
Typically, when rates have dropped 1% or more, you’ve built equity, your credit has improved, or your circumstances have changed. Therefore, get a professional assessment to confirm the benefit.
Refinancing a home loan is worth it when the savings over the time you will hold the loan are bigger than the costs of switching, such as break fees on a fixed term and any lender or legal fees. Common triggers are a lower rate, equity you can put to use, or high-interest debt you want to consolidate. We run the numbers for you during your review, so you can see the break-even point before you commit.
It depends on the lender and how quickly your documents arrive. I suggest starting four to six weeks before your fixed term ends, so there is no rush and no break fee.
You can refinance before the term ends (break fees may apply) or wait until it expires (no break fee). We help you calculate whether breaking the rate is worth it.
Absolutely. You can refinance and roll in other debts in one process. Importantly, we structure this carefully to avoid pitfalls.
Possible costs are legal fees, a valuation if the new lender wants one, any discharge or admin fees, and a break fee if you leave a fixed term early. A new lender’s cashback may cover some of these, but it can be clawed back if you leave within its minimum period. We add it all up for your loan during your review. See mortgage break fees for how the break fee is worked out.
Mortgage Refinancing Scenarios
Possibly, though lenders usually apply stricter criteria when you borrow above 80% of the property’s value, and policy varies by lender.
In many cases, refinancing is still possible. Moreover, we work with lenders experienced in assessing various credit histories. Admittedly, terms may be stricter, but options often exist. See Bad Credit Home Loans →
Definitely. Self-employed refinancing simply requires additional documentation (tax returns, GST records, P&L statements). Fortunately, we work with lenders experienced in self-employed lending. Self-Employed →
In most cases, yes. Refinancing to access equity for renovations is common. Typically, released equity is cheaper than renovation loans or personal loans, subject to lender assessment.
Certainly. Portfolio refinancing is complex but achievable. Specifically, we help structure across lenders for optimal flexibility. Investment Loans →
Often, yes. Refinancing to a shorter term (e.g. 15 years instead of 20) suits borrowers wanting faster payoff and reduced total interest, subject to lender assessment.
★★★★★
“Mortgage Sense helped us refinance and reduce our repayments. The process was straightforward, and we understood every step. The adviser answered all our questions and made us feel confident in the decision.”
— NZ Homeowner
Our Promise
We Provide Clear, Transparent Advice
Above all, here’s what we promise: if refinancing doesn’t make financial sense for you, we’ll be direct about it. We’ll explain why, show you the numbers, and recommend staying with your current lender if that’s genuinely the better option.
Ultimately, a professional assessment provides clarity without obligation. You’ll understand your options and whether refinancing genuinely benefits you long-term.
The information on this page is general in nature and is intended for educational purposes only. It does not take into account your individual objectives, financial situation or needs. Lending is subject to individual lender criteria, credit assessment and approval. Past performance is not indicative of future results. Interest rates and lending terms vary by lender. For financial advice tailored to your circumstances, speak with your mortgage adviser or a licensed financial adviser. Yatin Kainth is a Financial Adviser at Mortgage Sense. Disclosure Statement | Fees & Commissions